Running a small business successfully requires more than generating sales and attracting new customers. Business owners must also understand how effectively they manage their finances. Even a company with increasing revenue can face financial difficulties if expenses are uncontrolled, customer payments are delayed or debts continue to increase.
This is where financial analysis becomes important. Understanding the financial position of a business helps owners make better decisions, manage risks and plan for future growth. However, many small business owners focus only on monthly sales and bank balances without analysing the actual financial performance of their companies.
Financial Ratios for Small Businesses provide a practical way to understand financial health. These ratios convert accounting information into meaningful measurements that explain profitability, liquidity, efficiency and debt management.
For example, a business may generate ₹10 lakh in monthly revenue but retain only ₹50,000 as profit. Another business with lower revenue may achieve better profitability because it manages expenses efficiently. Financial ratios help identify these differences.
By monitoring the right financial indicators every month, business owners can identify potential problems early, control unnecessary expenses and make informed financial decisions.
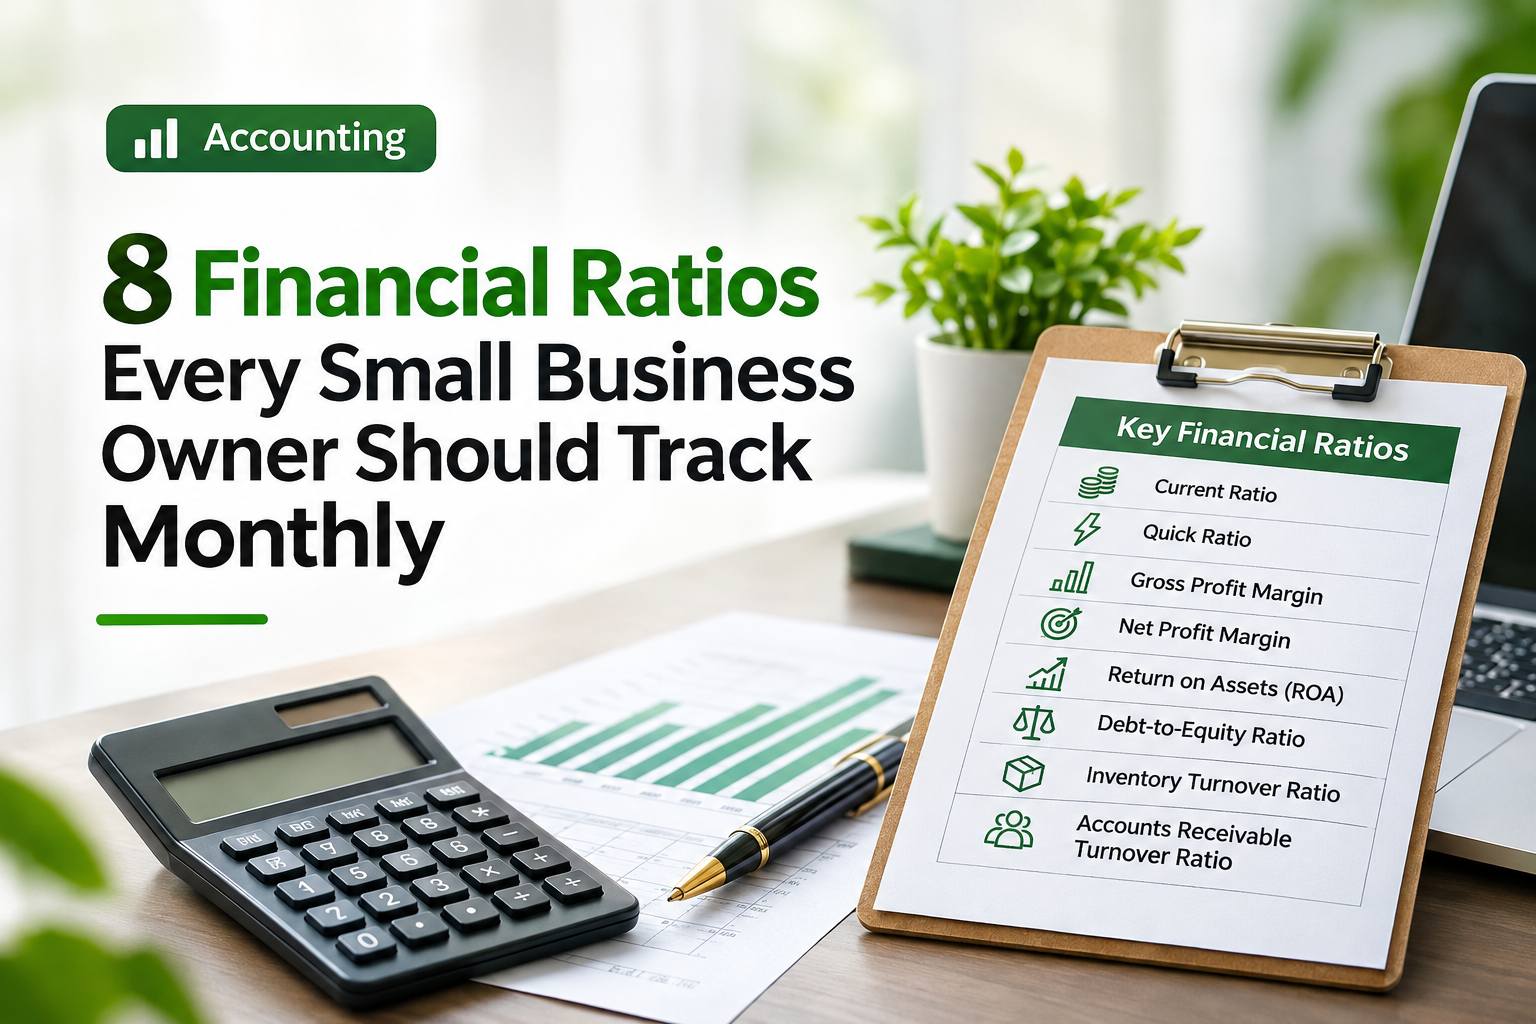
In this article, we will explore eight important financial ratios every small business owner should track monthly, including their formulas, practical examples and benefits.
What Are Financial Ratios?
Financial ratios are calculations that compare two or more financial figures from a company's accounting statements. They help evaluate the financial performance and stability of a business.
These calculations generally use information from three important financial statements:
-
Balance Sheet: Shows the company's assets, liabilities and equity.
-
Income Statement: Displays revenue, expenses and profit over a specific period.
-
Cash Flow Statement: Explains how money enters and leaves the business.
Financial ratios make it easier to understand complex accounting information. Instead of looking at individual numbers, business owners can evaluate relationships between different financial elements.
There are four major categories of financial ratios:
-
Liquidity Ratios: Measure the ability to pay short-term obligations.
-
Profitability Ratios: Evaluate how effectively a business generates profit.
-
Efficiency Ratios: Measure how efficiently resources are being used.
-
Leverage Ratios: Evaluate the company's dependence on borrowed funds.
Understanding these categories helps business owners identify which areas require more attention.
Why Should Small Businesses Track Financial Ratios Monthly?
Many businesses review their financial performance only during annual accounting or tax preparation. However, waiting until the end of the financial year can make it difficult to identify problems early.
Tracking Financial Ratios for Small Businesses every month provides a clearer understanding of financial performance and supports better business management.
Here are some important benefits.
1. Better Financial Planning
Monthly financial analysis helps business owners understand income, expenses, liabilities and available resources. This information supports realistic budgets and future financial planning.
2. Early Identification of Financial Problems
A declining profit margin or increasing debt ratio may indicate financial difficulties. Regular monitoring helps identify these warning signs before they become serious.
3. Improved Cash Flow Management
Businesses need sufficient cash to pay employees, suppliers, rent and other operating expenses. Financial ratios help owners evaluate whether their available resources are sufficient.
4. Smarter Business Decisions
Financial information helps owners decide whether to invest in equipment, expand operations, hire employees or reduce unnecessary expenses.
5. Better Loan and Investment Preparation
Banks and financial institutions often examine financial performance when evaluating loan applications. Maintaining accurate financial records and understanding important ratios can help businesses prepare for financial discussions.
8 Financial Ratios Every Small Business Owner Should Track Monthly
The following eight financial ratios provide useful insights into different areas of business performance. Business owners should select the ratios relevant to their industry and review them consistently.
1. Current Ratio – Measure Your Short-Term Financial Stability
The current ratio is one of the most important liquidity ratios. It measures whether a business has enough current assets to cover its short-term financial obligations.
Current assets generally include cash, bank balances, accounts receivable and inventory. Current liabilities include supplier payments, short-term loans and other obligations payable within one year.
Formula:
Current Ratio = Current Assets ÷ Current Liabilities
Practical Example:
Suppose a small business has:
-
Current Assets: ₹10,00,000
-
Current Liabilities: ₹5,00,000
Current Ratio = 10,00,000 ÷ 5,00,000
Current Ratio = 2:1
This means the business has ₹2 in current assets for every ₹1 of current liabilities.
Why Should You Track It Monthly?
A declining current ratio may indicate that the business is struggling to manage short-term financial obligations. Monitoring it regularly helps owners maintain sufficient working capital.
However, a very high current ratio is not necessarily positive. It may indicate that cash or inventory is not being used efficiently. The ideal ratio depends on the company's industry and operating cycle.
2. Quick Ratio – Understand Your Immediate Payment Capacity
The quick ratio, also known as the acid-test ratio, measures whether a business can meet its short-term liabilities using its most liquid assets.
Unlike the current ratio, it excludes inventory and prepaid expenses because these assets may not be immediately available to pay outstanding obligations.
Formula:
Quick Ratio = (Current Assets − Inventory − Prepaid Expenses) ÷ Current Liabilities
Practical Example:
Consider a business with:
-
Current Assets: ₹8,00,000
-
Inventory: ₹2,00,000
-
Prepaid Expenses: ₹50,000
-
Current Liabilities: ₹4,00,000
Quick Ratio = (8,00,000 − 2,00,000 − 50,000) ÷ 4,00,000
Quick Ratio = 1.375
This means the company has approximately ₹1.38 in quick assets for every ₹1 of current liabilities.
Why Should You Track It Monthly?
The quick ratio helps business owners understand whether they can manage immediate payments without depending on selling inventory.
It is particularly useful for retail stores, wholesalers and businesses that maintain significant stock.
If the quick ratio decreases consistently, owners should review outstanding payments, available cash and short-term financial commitments.
3. Gross Profit Margin – Evaluate Your Product or Service Profitability
Gross profit margin measures how much revenue remains after deducting the direct costs associated with producing goods or delivering services.
It helps business owners understand whether their pricing strategy and direct costs support profitable operations.
Formula:
Gross Profit Margin = (Gross Profit ÷ Revenue) × 100
Gross Profit = Revenue − Cost of Goods Sold
Practical Example:
Suppose a retail business generates ₹10,00,000 in monthly revenue and spends ₹6,00,000 on the cost of goods sold.
Gross Profit = ₹10,00,000 − ₹6,00,000
Gross Profit = ₹4,00,000
Gross Profit Margin = (4,00,000 ÷ 10,00,000) × 100
Gross Profit Margin = 40%
This means the business retains ₹40 as gross profit for every ₹100 in revenue before operating expenses and other costs.
Why Should You Track It Monthly?
A declining gross profit margin may indicate:
-
Increasing supplier prices.
-
Higher production expenses.
-
Excessive discounts.
-
Incorrect product pricing.
-
Rising direct labour costs.
By reviewing this ratio monthly, business owners can adjust pricing strategies, negotiate with suppliers and control direct expenses.
4. Net Profit Margin – Understand Your Actual Business Profit
Generating high revenue does not always mean a business is financially successful. A company may record significant sales but spend too much on salaries, rent, marketing, transportation and administrative expenses.
Net profit margin measures the percentage of revenue that remains as profit after accounting for expenses, interest and taxes.
Formula:
Net Profit Margin = (Net Profit ÷ Revenue) × 100
Practical Example:
A small business records:
-
Monthly Revenue: ₹12,00,000
-
Total Expenses: ₹10,20,000
-
Net Profit: ₹1,80,000
Net Profit Margin = (1,80,000 ÷ 12,00,000) × 100
Net Profit Margin = 15%
This means the company earns ₹15 in net profit for every ₹100 in revenue.
Why Should You Track It Monthly?
Net profit margin helps business owners understand whether their company is converting sales into actual earnings.
If revenue increases but net profit margin decreases, expenses may be growing faster than sales.
Monthly monitoring helps identify unnecessary spending, evaluate pricing decisions and improve overall profitability.
5. Return on Assets (ROA) – Measure How Effectively You Use Business Assets
Return on Assets (ROA) measures how effectively a business uses its assets to generate profit.
Business assets may include machinery, equipment, buildings, inventory, cash and other resources owned by the company.
Formula:
Return on Assets = (Net Profit ÷ Average Total Assets) × 100
Average Total Assets = (Opening Total Assets + Closing Total Assets) ÷ 2
Practical Example:
Suppose a business has:
-
Net Profit: ₹3,00,000
-
Average Total Assets: ₹15,00,000
ROA = (3,00,000 ÷ 15,00,000) × 100
ROA = 20%
This means the business generates ₹20 in net profit for every ₹100 invested in assets.
Why Should You Track It Monthly?
ROA helps business owners evaluate whether their assets are contributing effectively to profitability.
For example, if a company invests in expensive machinery but does not experience an improvement in production or revenue, its asset efficiency may decline.
Regular monitoring helps identify underutilised resources and supports better investment decisions.
6. Debt-to-Equity Ratio – Monitor Your Business Borrowings
The debt-to-equity ratio measures the relationship between a company's total debt and shareholders' equity.
It helps business owners understand how much of the business is financed through borrowing compared with the funds invested by owners or shareholders.
Formula:
Debt-to-Equity Ratio = Total Debt ÷ Shareholders' Equity
Practical Example:
A company has:
-
Total Debt: ₹8,00,000
-
Shareholders' Equity: ₹10,00,000
Debt-to-Equity Ratio = 8,00,000 ÷ 10,00,000
Debt-to-Equity Ratio = 0.8
This means the business has ₹0.80 in debt for every ₹1 of shareholders' equity.
Why Should You Track It Monthly?
A high debt-to-equity ratio may indicate that a business depends heavily on borrowed funds.
Regularly monitoring this ratio helps owners evaluate borrowing levels, manage repayment commitments and avoid unnecessary financial risks.
The appropriate level varies depending on the industry, business maturity and financing structure.
7. Inventory Turnover Ratio – Improve Your Stock Management
The inventory turnover ratio measures how frequently a business sells and replaces its inventory during a specific period.
It is particularly useful for retail stores, wholesalers, manufacturers and e-commerce businesses.
Formula:
Inventory Turnover Ratio = Cost of Goods Sold ÷ Average Inventory
Average Inventory = (Opening Inventory + Closing Inventory) ÷ 2
Practical Example:
Suppose a retail business records:
-
Monthly Cost of Goods Sold: ₹6,00,000
-
Average Inventory: ₹2,00,000
Inventory Turnover Ratio = 6,00,000 ÷ 2,00,000
Inventory Turnover Ratio = 3 times
This means the business has sold and replaced inventory approximately three times during the month, based on the stated calculation.
Why Should You Track It Monthly?
A low inventory turnover ratio may indicate slow-moving products, overstocking or weak customer demand.
On the other hand, an extremely high ratio may indicate insufficient stock, potentially resulting in missed sales opportunities.
Monthly monitoring helps businesses maintain appropriate inventory levels, reduce storage costs and improve purchasing decisions.
For service-based businesses without physical inventory, this ratio may not be relevant.
8. Accounts Receivable Turnover Ratio – Manage Customer Payments Efficiently
Many small businesses offer products or services on credit. Although credit sales can attract customers and increase revenue, delayed payments can create serious cash flow problems.
The accounts receivable turnover ratio measures how efficiently a business collects outstanding payments from customers.
Formula:
Accounts Receivable Turnover Ratio = Net Credit Sales ÷ Average Accounts Receivable
Practical Example:
Suppose a business records:
-
Monthly Net Credit Sales: ₹9,00,000
-
Average Accounts Receivable: ₹3,00,000
Accounts Receivable Turnover Ratio = 9,00,000 ÷ 3,00,000
Accounts Receivable Turnover Ratio = 3 times
This indicates that monthly credit sales are three times the average outstanding receivables during the period.
Why Should You Track It Monthly?
A declining receivables turnover ratio may indicate that customers are taking longer to pay their invoices.
This can affect the company's ability to pay suppliers, employees and other operating expenses.
Regular monitoring helps businesses improve payment follow-ups, establish clear credit policies and reduce overdue customer balances.
How to Use Financial Ratios to Improve Business Performance
Calculating financial ratios is only the first step. Their real value comes from using the results to improve business operations.
Here are five practical ways to use Financial Ratios for Small Businesses effectively.
1. Compare Monthly Performance
Compare the current month's financial ratios with previous months. This helps identify trends and understand whether the business is improving or experiencing difficulties.
2. Set Realistic Financial Targets
Establish financial targets based on your business model, industry and previous performance. For example, you may aim to improve gross profit margin or reduce outstanding customer payments.
3. Identify Areas That Need Improvement
If net profit margin decreases, review operating expenses. If the quick ratio becomes weaker, examine available cash and short-term liabilities.
4. Maintain Accurate Financial Records
Financial ratios are only as reliable as the accounting information used to calculate them. Maintain updated balance sheets, income statements and cash flow records.
5. Seek Professional Financial Guidance
An accountant or financial professional can help interpret financial ratios, identify potential risks and develop strategies for improving financial performance.
Common Mistakes to Avoid When Tracking Financial Ratios
Although financial ratios are useful, incorrect interpretation can lead to poor business decisions.
Some common mistakes include:
-
Analysing only one ratio: A single ratio cannot explain the complete financial position of a company.
-
Ignoring industry differences: Financial benchmarks vary between retail, manufacturing, service and technology businesses.
-
Using inaccurate accounting data: Incorrect financial records produce misleading results.
-
Ignoring monthly trends: Comparing ratios across different periods provides more meaningful insights.
-
Confusing profit with cash flow: A profitable business may still experience cash shortages because of delayed customer payments.
-
Not taking corrective action: Monitoring financial performance is useful only when businesses act on the findings.
A balanced approach that considers liquidity, profitability, efficiency and debt provides a more complete understanding of business financial health.
How Clockwell International Supports Better Financial Management
Managing business finances requires accurate accounting, regular financial reviews and a clear understanding of financial performance.
Clockwell International supports businesses with professional business and financial guidance, helping business owners make informed decisions and maintain better control over their operations.
From accounting and financial management to business compliance and advisory services, professional guidance can help businesses understand their financial position and plan for sustainable growth.
Whether you operate a startup, small business or growing company, understanding your financial numbers is essential for long-term success.
With proper financial planning and consistent performance monitoring, businesses can identify opportunities, manage financial risks and build a stronger foundation for growth.
Published on November 12, 2026